Fleet tax and reporting
Business fleet vehicle classification and tax updates
Recent changes to HMRC vehicle classification impact how finance directors calculate tax liability and report business travel costs for company fleets.
 Alison DavidsonHead of Finance
7 min readUpdated
What matters here
- HMRC has updated classification standards for dual purpose vehicles.
- Finance teams must reassess fleet inventory for benefit in kind accuracy.
- Correct classification prevents significant retrospective tax adjustments.
In short
HMRC has adjusted the criteria for classifying double cab pickups as company cars rather than vans. This change significantly alters the benefit in kind liability for employees and the employer's national insurance obligations. Finance directors must now re-audit their fleet composition to ensure each vehicle is categorised against the latest technical specifications to maintain tax compliance. Precise adherence to these updated definitions is mandatory to avoid retrospective tax adjustments and potential penalties arising from misclassification during payroll processing.
The shift represents a tightening of the interpretation regarding payload capacities. For many organisations, this implies that double cab models—previously treated as commercial assets under the van benefit rules—now fall under the more rigorous company car tax framework. This necessitates an immediate review of every asset on the fleet register to ensure payroll accuracy for the current and future tax years.
The shift in vehicle classification criteria
HMRC has recently clarified the technical standards used to distinguish between light commercial vehicles and passenger cars. This distinction carries significant weight for finance departments managing measuring and managing your business fleet emissions. Historically, certain double cab pickups were treated as commercial vehicles, which offered a favourable tax outcome compared to company cars. The current guidance relies more heavily on payload capacity and the primary design purpose of the vehicle.
Finance directors should note that vehicles with a payload of one tonne or more are no longer automatically classed as vans for all tax purposes. This development means that many vehicles previously treated as commercial assets must now be assessed under the benefit in kind (BIK) regime. The change is intended to standardise how vehicles are treated in payroll and ensures that the tax treatment reflects the actual utility of the transport assets.
For teams managing corporate mobility, this requires a manual review of every vehicle asset in the fleet. Reliance on previous historical classification is no longer sufficient. Failure to adjust this data can result in systemic under-reporting of taxable benefits, leading to potential reconciliation issues during year-end audit cycles. Practitioners must check the manufacturer's technical specifications sheet for the precise payload, as even minor modifications or aftermarket additions do not typically alter the legal classification of the vehicle for tax purposes.
Financial impact on the payroll ledger
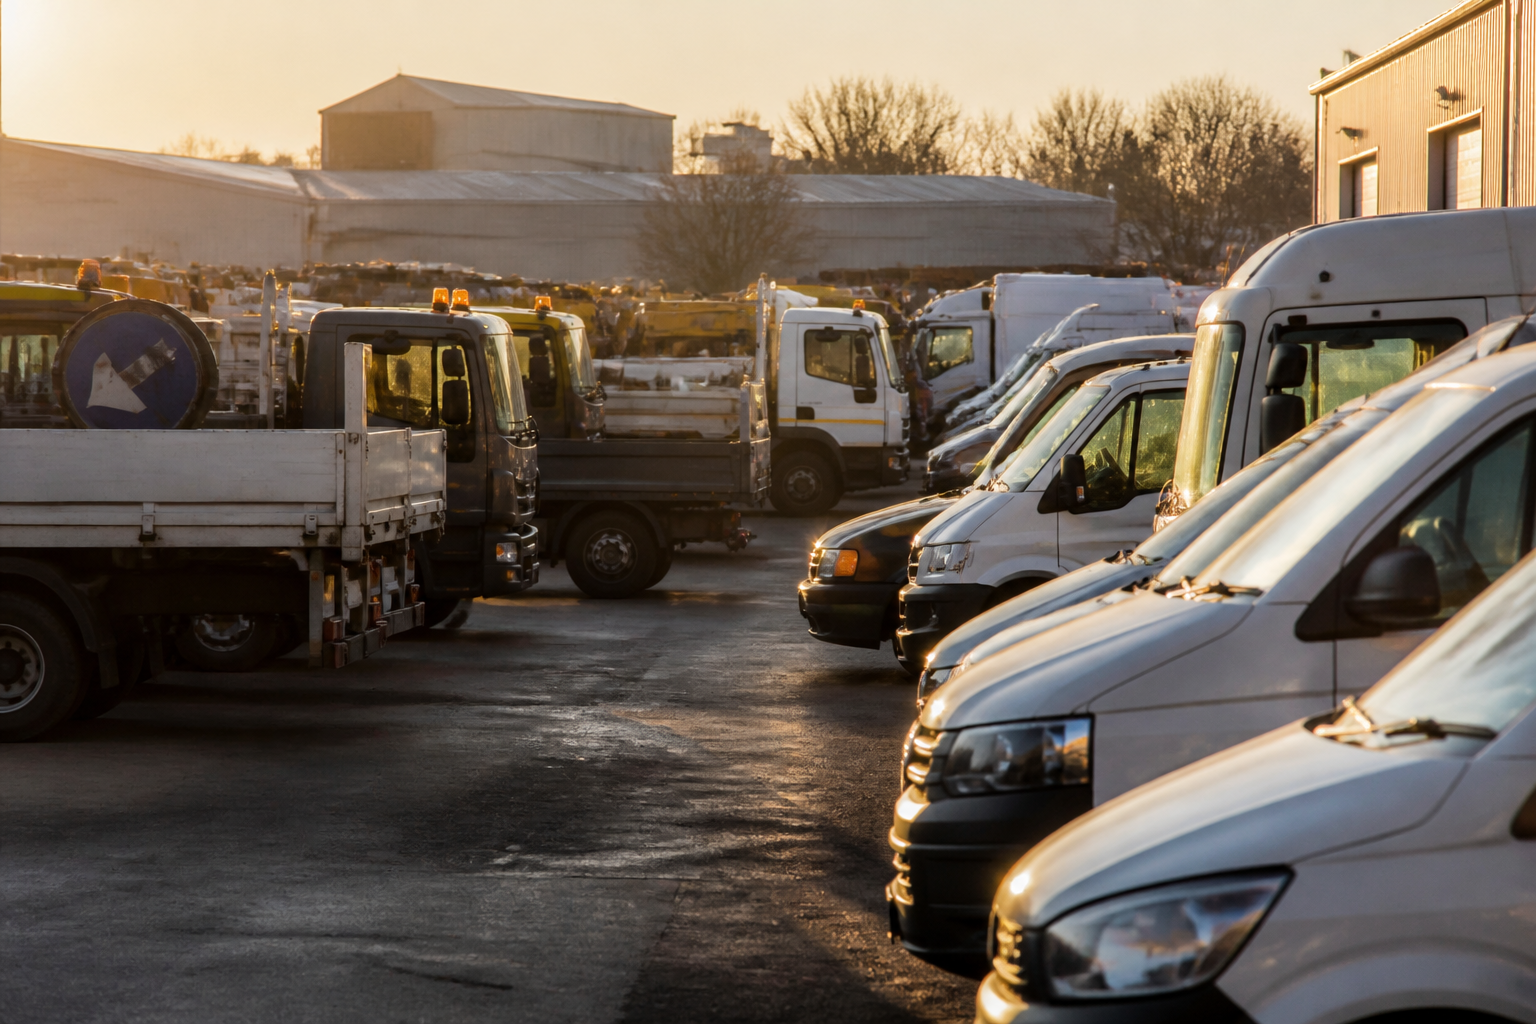
The movement of vehicles from commercial status to company car status triggers an immediate change in the tax burden for employees. As a company car, a vehicle attracts a BIK rate determined by its carbon dioxide emissions, fuel type, and list price. This contrasts with the fixed-rate van benefit, which is often significantly lower. Employees who were previously paying tax on a nominal van benefit may face a sharp increase in their monthly tax deductions.
Employers must communicate these changes clearly to affected staff. Transparency is essential to maintain trust in our schemes. Finance teams need to model the new tax scenarios for each affected employee to prevent surprise deductions from payroll. Providing clear documentation of why the change occurred, based on the updated HMRC guidelines, is the best approach to managing internal enquiries and expectations. Modelling should include the P11D value, which incorporates the list price, delivery charges, and any non-standard accessories.
From an accounting perspective, this transition also impacts the employer's Class 1A national insurance contributions. Because the benefit value is higher for a passenger car than for a commercial van, the employer will see an increase in the total NI cost for each affected vehicle. These costs should be incorporated into the current annual budget to avoid mid-year deficits. Where vehicles are pooled, the complexity of apportioning BIK increases, requiring robust software logic to ensure individual employees are taxed accurately based on their specific access to the vehicle.
| Vehicle Type | Old Classification | New Classification | Tax Basis |
|---|---|---|---|
| Double Cab | Van | Car | BIK Rate |
| Utility Pick-up | Van | Car | BIK Rate |
Illustrative figures based on general HMRC classification trends.
Audit and compliance for finance teams
A robust audit strategy starts with the vehicle handbook and the technical specification sheet for every unit in the fleet. Finance managers should look specifically for the payload metric. If a vehicle has a payload capacity under the threshold defined by HMRC, it should be flagged for immediate reclassification. This audit should be documented in the company's internal risk register to demonstrate proactive compliance with about Net Zero Benefits and broader HMRC requirements.
The audit process should also consider the impact on a practical guide to electric vehicle leasing for employees. Where an employee has selected an electric vehicle through a salary sacrifice arrangement, the tax calculation is already highly efficient. However, the reclassification of non-electric vehicles requires a recalculation of the BIK percentage. This is a good time to discuss the benefits of moving toward an electric-only fleet, as the BIK rates for battery electric vehicles remain historically low and stable. Finance teams should cross-reference vehicle registration documents (V5C) against internal asset registers during this audit to identify discrepancies.
Finance directors should engage with their payroll software providers to ensure the system is correctly configured to apply the new tax rates. Automated systems often use historical classification codes which may now be obsolete. Manual overrides may be necessary for the current tax year to bridge the gap while system settings are updated. Ensure that your payroll process includes a verification step for all new vehicle additions to the fleet, requiring procurement teams to input payload data at the point of ordering.
A robust audit strategy starts with the vehicle handbook and the technical specification sheet for every unit in the fleet.
Risk mitigation and payroll management
The primary risk of failing to reclassify is the potential for an HMRC enquiry and subsequent penalties. HMRC has a standard expectation that employers will correct tax reporting errors as soon as they become aware of them. If an employer continues to report a vehicle as a van after it is clearly a car by the new definition, they are effectively under-paying national insurance. This liability can accumulate quickly over a large fleet, potentially leading to significant back-dated charges plus interest.
Proactive management involves reviewing the The Electric Car Scheme assets already in the fleet. While electric vehicles typically have lower BIK liabilities, they are still subject to the same classification rules regarding body type and design. An employee in an electric double cab should be taxed based on the car benefit rules, just as they would be for an internal combustion engine vehicle. This is often where confusion arises, as the low BIK rate for electric vehicles can mask the underlying classification error.
Beyond tax, consider the implications for insurance premiums. Some fleet insurance policies have different premiums for cars and vans. Updating your vehicle register ensures that your insurance coverage remains valid. If an accident were to occur in a vehicle that was misclassified on the internal register, the insurer might dispute the claim based on incorrect information. Coordinate with your insurance broker as soon as the internal audit is complete to synchronise classification data across tax and risk management platforms.
Communicating with staff
Finance teams often worry about the reaction of employees to sudden changes in take-home pay. The best mitigation is direct, factual communication. Explain that this is a change in government classification rules, not a company policy change. Use a simple table to show the 'before' and 'after' figures for a representative vehicle in the fleet. This removes ambiguity and shows that the company is managing the issue systematically. Employees should receive written notice of the change, ideally with a projected timeline of payroll impacts.
When talking to employees, highlight the potential to offset increased tax costs by choosing a more efficient vehicle. Many employees find that moving from a high-emission diesel vehicle to an electric model significantly reduces their total monthly cost, even with the new car tax rules applied. This is an opportunity to discuss the broader benefits of The Electric Car Scheme as a solution for both the employee and the business. Providing illustrative scenarios helps staff weigh their options.
Keep a log of all communications sent to employees regarding this issue. If HMRC ever conducts an audit of your payroll processes, this log serves as evidence that you acted in good faith to inform your workforce of the regulatory changes. It also provides a paper trail for the adjustments made to payroll records. Ensure that HR and payroll departments are aligned in their messaging to avoid contradictory information reaching the workforce.
Long-term fleet strategy
The recent HMRC classification adjustment should inform your future fleet procurement strategy. If the company is currently looking to replace vehicles, the financial benefit of 'van' status is less certain than it once was. Finance directors should factor in the car BIK rates for all potential new vehicle purchases during the budget planning phase. This ensures that you do not face unexpected tax burdens in two or three years if further regulatory shifts occur.
Consider the role of charging infrastructure in your fleet planning. Investing in The Charge Scheme can help reduce the total cost of ownership for electric vehicles, which in turn offsets the impact of any tax changes. A fleet that is primarily electric is less susceptible to changes in how internal combustion vehicles are taxed. Building this infrastructure now is a pragmatic step towards a lower-risk, more predictable fleet budget that aligns with predicting reward strategy shifts for the year ahead.
Finally, monitor any future announcements from HMRC regarding vehicle definitions. Policy in this area is designed to support the UK's broader objectives for road transport. Staying ahead of these changes requires a permanent line item in your finance calendar for 'fleet compliance review'. By institutionalising this review, you ensure that your fleet remains a manageable and cost-effective asset for the long term. This periodic check should extend to examining leasing contracts for potential break clauses or flexibility.
Questions people ask
- How do I know if my company's double cab pickup is now a car for tax purposes?
- Review the manufacturer's technical specifications for the vehicle. If the payload capacity is under one tonne, it is generally treated as a car. You must also consider the vehicle's primary design purpose. If in doubt, consult the updated HMRC guidance or seek advice from a professional tax advisor to ensure your classification is accurate.
- Does this reclassification affect the national insurance contributions for my business?
- Yes, moving a vehicle from van to car classification increases the benefit in kind value. As the benefit is higher, the employer's Class 1A national insurance contribution will rise. Finance departments should update their annual budgets to account for these additional payroll costs to avoid mid-year deficits caused by the change in status.
- Are electric double cabs also affected by these classification changes?
- Yes, the classification rules regarding body type, design, and payload apply to all vehicles regardless of fuel type. While electric vehicles benefit from lower BIK rates, an electric double cab will be taxed under car benefit rules if it meets the criteria. The lower BIK percentage can sometimes mask the impact, so verify all assets.
- What is the best way to handle payroll adjustments for affected staff?
- Communicate the changes proactively and transparently, explaining that the adjustment arises from HMRC policy updates rather than internal changes. Provide employees with clear, factual information and simple comparative tax tables. Offering The Electric Car Scheme as an alternative can help employees mitigate increased tax costs through improved vehicle efficiency and lower BIK rates.
- Could my fleet insurance be affected by the reclassification of vehicles?
- Yes, insurance premiums often vary between passenger cars and light commercial vehicles. If your internal register is not updated to reflect the new classification, you may be left with invalid insurance coverage. Contact your broker immediately after your internal audit is complete to ensure your policy accurately reflects the vehicle types within your business fleet.
Keep reading
UK household financial health
Mapping modern household expenditure patterns
electric vehicle charging logistics
Myths and facts about UK electric vehicle charging
Green technology sector skills
Skills and capacity in the green installation sector
employee reward strategy analysis
Balancing reward budget and employee choice
employee reward strategy analysis
Choosing between salary sacrifice and personal car finance
electricity grid connection reform
Managing grid connection risks for commercial energy projects
Home heating technology update
Domestic heat pump installation process
Home solar energy generation
Myths and facts about home solar energy
Household energy price trends